how to save for short term and long term goals
Learn how to save for short-term and long-term goals, build an emergency fund, divide your income, choose where to keep your savings, and create a plan that actually works.
How to save for long term and short term goals
How to save for long term and short term goals is a strategy everyone who is looking to be financially free from pressure and long term growth need to have.
Learning how to save for both long term and short term
Saving money without a systematic goal is like driving without a destination, you think the process is grinding, but without a goal you may get burnt out and the willpower may drop drastically, causing you to look for relaxation. The difference between people who consistently accumulate money and those who do not is not how much they earn, but whether they are clear about what they are saving for.
Related posts on financial freedom
A concrete goal turns savings into something meaningful, and also may create a complete change in the motivation or weather to keep the strategy going provided you see productivity.
In this article we explain how to define and plan savings goals in long term and short term. How to calculate how much you need to set aside each month to reach them, and how to manage several goals at once without the system falling apart.
Why you need set savings goals.
The human brain tends to struggle to engage with abstract objectives: telling yourself you want to save more or have more money does not actually activate any concrete action mechanism. Whilst on the other hand, when you tell yourself “I want to have $10,000 USD saved in 6 months to change my car”, it creates a clear mental image, a deadline, and a strong sense of commitment.
Related posts on financial freedom
When you set up financial savings goals, it also helps you make more conscious decisions day-to-day. When you know that every dollar you save this month brings you closer to your next goal, impulsive spending loses its appeal and saving gains meaning.
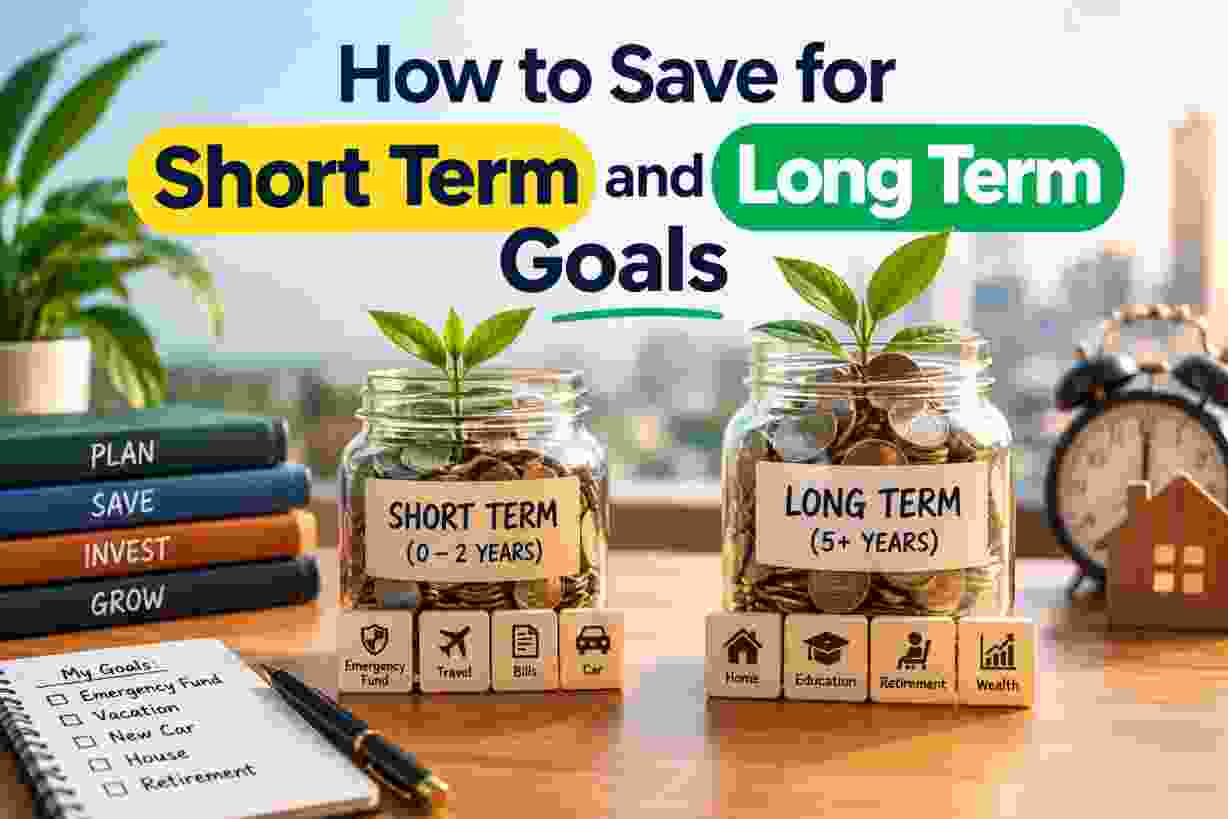
Short-term Savings goals: 0 to 12 Months
Short-term goals are the ones you want to reach in less than a year. They are the most important, the most motivating, and also the easiest to plan because the time horizon is close and uncertainty is very low.
An example of short-term goals are an initial emergency fund, paid off birthday, a vacation, a household appliance you need to replace, a training course or project, seasonal gifts or any seasonal expense you can anticipate.
How to turn $1 USD to $1 million. A related articles
Emergency Fund: This is the first short term goal you should strive for. It’s the foundational framework to starting a savings strategy.
For short term goals, a separate bank account need to be allocated to it. You do not need any complex financial product. What matters is that the money is physically separate from the main account so you don’t spend it without noticing.
Medium-term Savings goals: 1 to 5 years
Medium-term goals are those that require between one and five years of continuous saving. These are larger objectives that you cannot achieve in a few months, but aren’t out of sight.
An example of medium-term goals are a deposit for a flat, a new car, buying a used car of a certain value, a major home renovation, a long trip or round-the-world journey, or a savings cushion to launch personal project.
A high-yield savings account, a fixed-term deposit, or a low-risk investment fund can generate additional returns that accelerate achieving the goal without having to even contribute physically more each month.
The main key for medium-term goals is consistency. The biggest risk is not failing to save enough in one specific month, but abandoning the habit for several months in a row. That is why it is essential to automate the monthly contribution from day one.
Long-term savings goals: More than 5 years
Long-term goals are those that extend beyond 5 years. They are those that most important from a financial standpoint because systematically give us the greatest impact on your future economic situation, but they are also the hardest to sustain because the time horizon is so distant that can be hard to picture.
Most times these are saving for freedom, for retirement, or a big project that has always been on your mind for a long time. This is also a relaxed saving strategy as it gives you room to put in average effort and also allow it to grow exponentially.
How to calculate how much you need to save each month
This calculation is simple: divide the total amount of the goal by the number of months until the target date. That gives you the monthly contribution needed without any return.
For example: If you intend saving $10,000 in 3 years (36 months), you need to set aside $278 a month. If you want to save $24,000 in 5 years (60 months), the monthly contribution is $400.
In other words, when you earn a minimum of $100 maybe daily, weekly or even monthly and we invest $80 dollars out of it, this may sound crazy but that is what investment or saving is all about. Because if you are to look at it closely you will find out that you can actually survive very fine with just 20 bucks ($20) in your wallet.
If you know you cannot survive on 20% for 80% invested, then you need to reduce the rate of investment in order not to suffocate yourself along the line. But if you are new to this kind of investment strategy you need to make your mind up and be determined to save because it is with God and your determination can you prevail in whatever you set your eyes to achieve.
Common mistakes when planning savings goals
Knowing the most common mistakes helps you avoid them from the start and keep the plan active longer.
Not writing them down
A goal that only exists in your head is much easier to forget or abandon. Write each goal with its name, amount, deadline and monthly contribution. The simple act of writing it down significantly increases the likelihood of achieving it.
Setting too many goals at once:
having 8 simultaneous objectives with small contributions for each creates a feeling of making no progress on any of them. It is better to focus on 2 or 3 active goals and add new ones as each one is completed.
Not reviewing goals periodically:
Your situation changes. A goal that was a priority a year ago may have lost relevance, and a new more urgent need may have appeared. Review your goals at least every 6 months.
Mixing money from different goals:
If you have holiday money, the emergency fund and car savings all in the same account, it is very easy to spend it without noticing. Use separate accounts or digital envelopes for each important goal.
Giving up after the first stumble:
There will be months when you cannot make the full contribution. That does not mean the plan has failed. Reduce the contribution that month if necessary, but do not cancel the goal. Imperfect consistency always beats abandonment.
Planning your savings goals is the bridge between having a budget and having a financial future with direction. If you want to know how to maintain the savings habit month after month in a practical way, check out our guide on how to save money every month. And if you want to assess whether your current financial situation allows you to move towards your goals with solid foundations, review the 5 financial health signs we have developed.
Final thoughts
if you are not hungry enough you will not eat fine. So try to raise your risk appetite in other to get the best out of you. You need to take a higher risk in order to achieve a higher result. If you are willing to risk investing 80% of your weekly or monthly earnings knowing fully well that you will have to live beyond your earnings, that alone has solved 90% of your future problems without you knowing it. There will be a time when you are getting old and with bigger responsibilities you may not have the opportunity to acquire this wealth aggressively as you are in your hustling age now.
So the earlier you move the better. Our money needs to be working for us while we sleep. That’s where the result truly comes out. Money does not have emotions it only respect those who know how it operates and are ready to move in its direction. A lot of people work hard and get little or no result then get emotional about it thinking money will one day answer to those emotions, but money those not work like that. Money values those who seek to understand it and work in accordance to it.