Best Ways to Save Money and Earn Interest: Where Should I invest my Money?
Introduction
Best ways to save money and earn interest: where should I invest my money?. Yes, Saving money is very important, but when you simply keep money aside it is no longer the whole strategy
Usually the place you keep your money matters a lot and also determine how fast you invested returns can be multiplied. Imagine someone invests $10,000 in a low-interest savings account he or she could earn dramatically less than someone who puts the same amount in a competitive high-yield savings account, assuming the rates remain available.
The national average savings account rate is around 0.38% APY, while most high-yield savings accounts usually offer a higher rates above 4%. Current ranking offers can reach around 4.2% to 4.5%, although rates vary by institution and can change at any time.
That difference raises an important question:
What is the best way to save money and earn interest without taking unnecessary risks?
The answer depends on three things: when you need the money, how accessible it needs to be, and how much risk you can afford to take.
For most people, the smartest approach isn’t putting every dollar into one financial product. Instead, divide your money according to its purpose.
Related articles: how to save for short term and long term goals
This article will explain all that you need to know and how to plan yourself better. Best ways to save money and earn interest: where should I invest my money?
What Is the Best Way to Save Money and Earn Interest?
For the money that is meant for short term savings, the simplest approach to this is to use a high-yield savings account (HYSA) at an FDIC-insured bank or an appropriate federally insured credit union.
A high-yield savings account usually work like a traditional savings account, but it gives you the opportunity to earn even higher at the end of a specific period of time.
For example, some competitive high-yield savings accounts usually offer 4% APY, compared to a normal national savings that average at about 0.38%. That’s not to say that you should blindly select that is widely spoken about.
You should also consider the following:
- You need to observe if the institution is FDIC- or NCUA-insured.
- Check for the minimum balance requirements
- Check closely for the monthly fees
- Verify the withdrawal rules
- Verify the transfer speed
- Verify if the advertised APY has conditions or not and try to understand the policies involved.
- Observe if the rate is promotional
- Customer service
- Whether the account is convenient enough for you to actually use
The best savings account isn’t necessarily the one with the highest number on the screen. It is the one that provides a competitive return while keeping your money appropriately accessible and protected. Best ways to save money and earn interest: where should I invest my money?
Related articles: how to save for short term and long term goals
Why you’re savings account interest rate matters
Consider two people who each have $10,000. The first person keeps the money in an account earning 0.38% APY. While the second person keeps the money in an account earning 4.2% APY. While ignoring taxes, fees, rate changes and compounding differences, the approximate first-year interest would be:
$10,000 × 0.38% = $38
Compared to the other
$10,000 × 4.2% = $420
That’s a difference of approximately $382 in one year.
The moral is not for you to start chasing every high yield earning saving account because most of the times the rates do change.
The lesson is that the interest rate on the cash invested matters, especially when the balance of the account keeps growing. And the difference becomes more noticeable as you continue adding money.
Related articles: how to save for short term and long term goals
What Is APY?
Before making comparisons of different savings account, it’s important to understand APY.
APY stands for Annual Percentage Yield.
It is the amount of interest an account earns over a period of one (1) year while paying attention to the compounding yield overtime provided the rates remain the same. This is different from simply looking at an interest rate.
For example, if a bank advertises a 4.00% APY, that doesn’t mean you will keep earn that amount for the rest of your life. The rates in savings account usually changes overtime.
Banks can change rate based on market conditions and its own pricing decisions. So when choosing a bank consider the rates temporary and not a guaranteed long term returns. Best ways to save money and earn interest: where should I invest my money?
How Much Interest Can $1,000 Earn?
Let’s use our usually 4.00% APY to demonstrate this concept clearly.
For example you deposited $1,000 and the rate stayed at 4% APY, your balance can grow so high at an approximate figure of $1,040, that’s about $40 in interest before taxes, at $5,000 ($5,000 × 4% = approximately $200), at $10,000 ($10,000 × 4% = approximately $400), at $25,000 ($25,000 × 4% = approximately $1,000)
Mind you this are just illustrations, they are not a guarantee on your investment(s). Your exact earnings depend on the APY the bank is offering, the compounding, the account terms, the deposits, the withdrawals and how long the money remains in the account.
The important concept is simple:
The more money you save the more valuable a competitive interest rate becomes.
Where Should You Keep Your Savings?
There is no such place as the perfect place to keep you dollar. Everything in finance is designed to work for it sole purpose to which it was designed.
Here is a simple framework:
| Financial goal | Potential option |
| Emergency fund | High-yield savings account |
| Vacation within a year | HYSA |
| Upcoming major purchase | HYSA deposit account |
| Money needed in a few years | HYSA, CD or other cash product |
| Money you can lock away | Certificate of deposit |
| Long-term wealth | Diversified investments |
| Retirement | 401(k), IRA, etc. Fact check always |
The key is matching the product to the time horizon.
Investor.gov defines time horizon as the amount of time you need to reach a financial goal. It also emphasizes that the appropriate savings or investment product depends on when you’ll need the money and your risk tolerance. Best ways to save money and earn interest: where should I invest my money?
High-Yield Savings Accounts
A high-yield savings account can be particularly useful for money that needs to remain relatively accessible.
This makes it a natural candidate for:
- Emergency funds
- Short-term savings
- Vacation funds
- Car repair funds
- Home improvement money
- Upcoming bills
- Down-payment savings when the purchase is relatively near
The biggest advantage is the combination of liquidity and interest gained. You’re not necessarily required to lock your money away for months or years.
However, always check the specific account’s terms. Not every account offering a high APY has identical conditions. Some of the accounts may need a direct deposits, a minimum amount in the account and other required details.
Certificates of Deposit (CDs)
A certificate of deposit, or CD, is another way you can earn interest on money that is not needed short term.
With a certificate of Deposit (CD), all you need to agree is that your money be kept in the account for a specific period of time.
In exchange to this the bank will provide a stated interest rate for that account in terms of CD.
For example, here are the available CDs we may find:
- 3-month CDs
- 6-month CDs
- 1-year CDs
- 2-year CDs
- 5-year CDs
The major advantage is that it is easy to predict. While the disadvantage is has a reduced flexibility.
Usually premature withdrawals are not all that accepted, and therefore you may face a penalty for that or loose the interest already earned.
As at early this year, competitive U.S. CD rates were climbing to a figure of about 4%, although rates differ significantly by term and institution.
Don’t choose a CD simply because the advertised APY looks attractive.
You need to ask yourself this questions: “Will I need this money before the CD matures?” If the answer is yes, an accessible savings account may be more appropriate. Best ways to save money and earn interest: where should I invest my money?
Money Market Deposit Accounts
Money market deposit accounts can provide another place to hold cash while earning interest.
They can have features that make them somewhat different from traditional savings accounts, such as check-writing or debit-card access depending on the institution and account.
However, don’t confuse a money market deposit account with a money market mutual fund. They are different financial products.
FDIC insurance applies to qualifying bank deposit products, including savings accounts, money market deposit accounts and CDs at FDIC-insured institutions. Investment products such as mutual funds, stocks and bonds are not FDIC-insured.
U.S. Treasury Securities
For investors who are keen to investing for a short or medium term, they may look towards U.S. Treasury securities for a more beneficial outlook.
Treasury bills, notes and bonds are obligations of the U.S. government, but they are not FDIC-insured deposits. This detailed value is really important for investors.
The FDIC specifically states that Treasury securities are not covered by FDIC deposit insurance, even though they are backed by the U.S. government’s credit.
Treasuries can therefore belong in a broader cash-management strategy, but they shouldn’t simply be treated as interchangeable with a savings account. Best ways to save money and earn interest: where should I invest my money?
Investing for Long-Term Goals
Here’s where saving and investing become different.
If you intend saving for a period of one year, you don’t need to expose that money to volatile assets that may disrupt the value of that asset in a short period of time.
But if you’re saving for a goal like for a long period of time, then you need to look for a high rewarding asset to invest on instead of leaving it dormant in an account that is not yielding anything, which in turn may destroy your purchasing power. Volatility is not necessarily a problem here provided it has a good regulatory backing.
Investor.gov makes this distinction clearly. Usually short term goals requires you to sell at any point in time and so you may sell some share or part of your investment in market decline or upside. This may be beneficial at some point and can also lead to regrettable losses due to selling at a decline. For long-term goals, however, relying exclusively on low-return savings products may result in insufficient growth.
So you need to balance the priority accordingly.
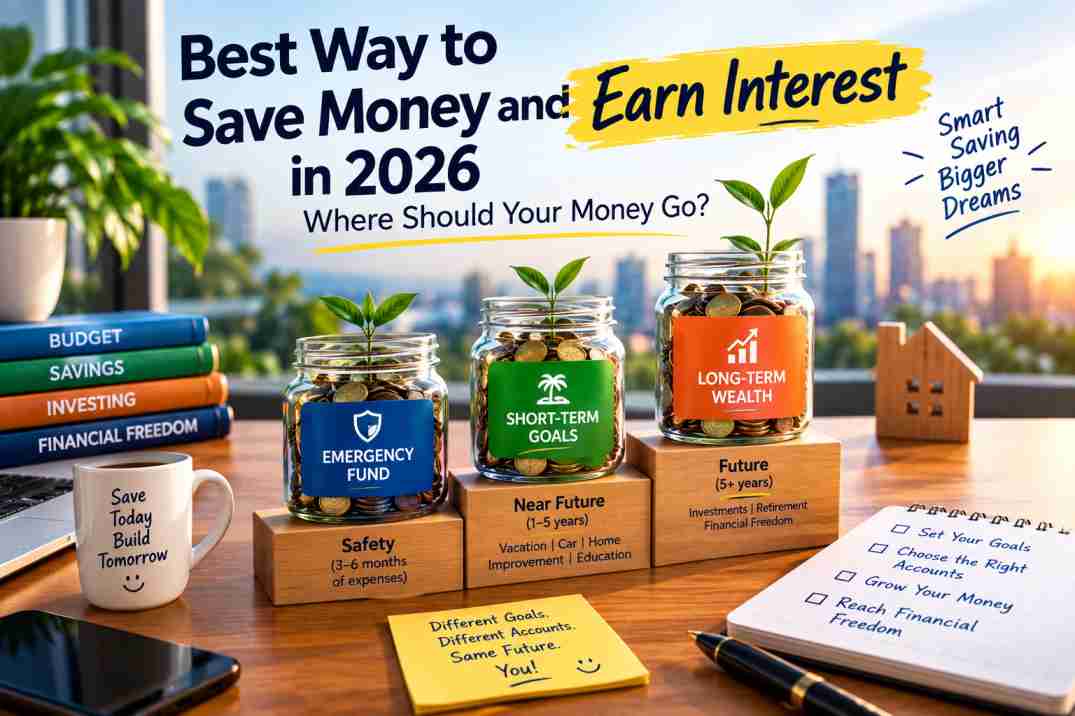
The 3-Bucket Strategy for Saving and Growing Your Money
One simple way to organize your finances is to divide your money into three.
Safety Money
This is money designed to protect you from financial emergencies.
Examples include:
- Job loss
- Medical expenses
- Major car repairs
- Emergency travel
- Urgent home repairs
- Unexpected bills
An emergency fund generally belongs in an accessible savings vehicle rather than a volatile investment.
Investor.gov notes that savings accounts can be appropriate for emergency funds and short-term needs. The exact amount you need depends on your circumstances. Some people aim for several months of essential expenses.
The important thing is that the money is available when you actually need it.
Short-Term Goals
This is money set aside for a particular purpose, such as Vacation, New car, Wedding, Home improvement, Education, Moving expenses, Large purchases.
If you expect to need the money within the next few years, protecting the principal may be more important than trying to maximize investment returns.
A CD could also make sense if the timing is predictable and you don’t need immediate access to the money.
Long-Term Wealth
This is money you’re unlikely to need for many years.
Examples include:
- Retirement
- Long-term wealth building
- Future financial independence
- Long-term education funding
- Other distant financial goalsd
Because you have more time, you may be able to accept more investment risk in exchange for greater potential growth.
This is where diversified investments can become more relevant.
But remember: Higher potential returns come with higher risk.
Investing isn’t a replacement for your emergency fund. You don’t want to be forced to sell an investment at an unfavorable time because your car broke down or your income varnished.
Related article: How to turn $1 dollar to 1 million dollars – numericnature
Should You Save Money or Invest It?
The answer is often:
You can do both—but for different purposes.
Imagine you have $20,000. You could put all $20,000 into investments.
But if you lose your job six weeks later and need $8,000 for living expenses, the stock market may be down at exactly the wrong time.
You might have to sell investments at a loss.
But, you could keep all $20,000 in cash. That gives you safety, but that could jeopardize you long term target.
You need to plan out your strategy well before execution.
For example:
Emergency money → accessible savings
Near-term goals → savings/CDs or other suitable low-volatility options
Long-term money → diversified investments
The exact percentages should depend on your income, expenses, debts, risk tolerance and goals.
How to Make Your Savings Grow Faster
Getting a higher APY is one part, the biggest part to enable you savings grow fast has to do with your rate of contribution.
Imagine you put in $100 per month in a savings account that is about $1200 per year. Someone saving $500 per month contributes $6,000 per year and another saves $1,000 per month that is about $12,000 per year, the interest will now be based on what has been contributed so far.
This is why improving your income and savings rate can be just as important as finding a better interest rate.
Instead of over evaluating the account that pays 4.10% over another that pays 4.20%, first you ask yourself:
“How can I consistently put more money into my savings?”
Automate Your Savings
One of the easiest ways to save consistently is automation. Instead of waiting until the end of the month to see what’s left, reverse the process.
When your pay-check arrives do this:
Income → Savings → Bills → Spending
How do I mean; I mean this, when you receive your salary or return of profits on goods purchased, you need to first Save before paying bills and then spend what is left. Not spend the income before considering to save.
Income → Spending → Whatever remains → Savings
You can set up recurring transfers from your checking account to your savings account.
Even $25 or $50 per paycheck can create a habit. As your income increases, increase the automatic transfer. Automation removes some of the emotional decision-making from saving.
Create Separate Savings Accounts for Different Goals
You don’t necessarily need dozens of bank accounts. But separating major goals can make saving easier.
For example: Emergency Fund, Vacation Fund, Car Fund, Home Fund, Long-Term Savings
When money has a name attached to it, you’re less likely to treat it as available spending money.
Some banks allow multiple savings buckets or subaccounts, which can make this strategy easier.
Don’t Chase the Highest APY Blindly
A high APY is attractive mostly for long term investment with compounding. But there are other things to look out for before investing your money or even creating an account.
Here are the steps to take:
- Is the institution insured: For bank deposits, verify that the bank is FDIC-insured. The standard FDIC insurance limit is $250,000 per depositor, per insured bank, for each ownership category.
- Are there monthly fees: A slightly higher APY may not be worth it if expensive fees consume your interest.
- Is there a minimum balance: Some accounts offer their best rate only if you meet certain requirements.
- Is the APY promotional: A promotional rate may not last indefinitely.
- How easy is it to access your money: If it’s an emergency fund, accessibility matters.
- Can the bank change the rate: Many savings accounts have variable rates.
How Much Money Should You Keep in Savings?
There isn’t one universal number. Your ideal savings balance depends on:
- Monthly essential expenses
- Job stability
- Number of income sources
- Family responsibilities
- Debt
- Insurance coverage
- Health and financial circumstances
- Upcoming major expenses
A person with a high stable income and low expenses may need a different emergency fund that is set aside than someone whose income fluctuates significantly.
Investor.gov notes that some people maintain enough savings to cover up to six months of income for emergencies, although the appropriate amount depends on individual circumstances.
What about Inflation?
Inflation is one of the night robbers of purchasing power. It creeps in to steal from you without you even knowing it. So that is the major reason you need to invest and save your money where inflation has zero or less effect on.
Peradventure you keep $10,000 in an account earning a very low rate while prices continue increasing.
Your account balance may technically rise slightly, but what that money can purchase could decline overtime. This doesn’t mean you should invest your emergency fund in stocks.
It means you need to recognize the tradeoff. Savings products prioritize safety and accessibility. Investments provide greater potential for long-term growth but introduce market risk.
Don’t Forget About Taxes on Interest
Interest earned in a taxable savings account generally isn’t free from taxes.
The IRS states that interest received or credited to an account that can generally be withdrawn without penalty is usually taxable income, subject to applicable exceptions. Banks and other payers generally report qualifying interest on Form 1099-INT.
This means that if your savings account earns $500 in interest, you shouldn’t automatically think of the entire $500 as money you get to keep after taxes.
Your actual tax treatment depends on your circumstances.
You should also remember that not receiving a Form 1099-INT doesn’t automatically mean taxable interest can be ignored. The IRS states that taxpayers must report taxable interest income even when they don’t receive the form.
For significant balances or complicated tax situations, consult a qualified tax professional.
What Is the Best Savings Strategy for Someone Starting From $0?
If you’re starting with nothing, don’t wait until you can save hundreds of dollars. Start with a manageable target.
For example: you start by saving $100 first, then you build it to $500, when you reach $1,000 that’s a milestone but it does not end there. You need to keep stacking up that emergency fund account. Then you strategize on sectioning your for short term and long term so that you will not end taking out funds out of emergency in a declining market. Once your financial foundation is stronger, direct appropriate money toward long-term investing.
The first goal is not maximizing interest. It is for you to build the habit. Once the habit is established, optimize the system.
The Biggest Mistake in investment: Treating All Money the Same
Your emergency fund and your retirement portfolio should not have the same job. Your vacation fund shouldn’t be invested the same way as money you won’t need for 30 years.
And money you need next month shouldn’t be exposed to the same risk as money you’re investing for decades.
Think about money in terms of time horizon. Do you need it soon? Then you prioritize on safety and access. Or do you need it in a few years? Then you Balance out the safety, access and the yield. Don’t need it for many years? Consider whether investing is appropriate for your goals and risk tolerance. That’s the foundation of a sensible savings strategy.
Final Thoughts:
The Best Way to Save Money and Earn Interest
The best way to save money and earn interest isn’t necessarily to find the account with the biggest advertised APY.
It’s to create a system where each dollar is matched to the right financial purpose.
For emergency funds and many short-term goals, a competitive high-yield savings account can offer an attractive combination of accessibility, safety and interest. Current U.S. rates in September 2026 show why comparing APYs can matter: some competitive HYSAs are offering more than 4%, while the national average savings rate is around 0.38%.
For money you can leave untouched for a defined period, CDs may be worth considering.
For certain investors, Treasury securities can provide another way to earn returns on appropriate funds, although they are not FDIC-insured deposits.
And for money you won’t need for many years, investing may provide greater long-term growth potential but with substantially more risk than a savings account.
This article is for educational purposes only and is not individualized financial, investment or tax advice. Interest rates and account terms change frequently. Always verify current APYs, fees, insurance coverage and account requirements directly with the financial institution before opening an account. Investment products can lose value.